Berkshire Hathaway buybacks surged to $9.6 billion in the third quarter of 2026, even as the company’s operating Profit declined nearly 6%. The results, released Saturday, November 7, highlighted a shift toward more aggressive share repurchases under Chief Executive Greg Abel, alongside mounting pressure on Berkshire’s insurance businesses.
The Omaha, Nebraska-based conglomerate reported operating earnings of $12.71 billion, down from $13.49 billion a year earlier. Despite the decline, Berkshire continued directing substantial capital toward its own shares, bringing total repurchases during the first nine months of 2026 to approximately $14.4 billion.
Berkshire Hathaway Buybacks Accelerate Under Greg Abel
Berkshire’s third-quarter repurchases were twice the approximately $4.8 billion spent during the first half of 2026. The company also purchased about $2 billion of additional shares during the first four weeks of October, extending its buyback activity beyond the reporting period.
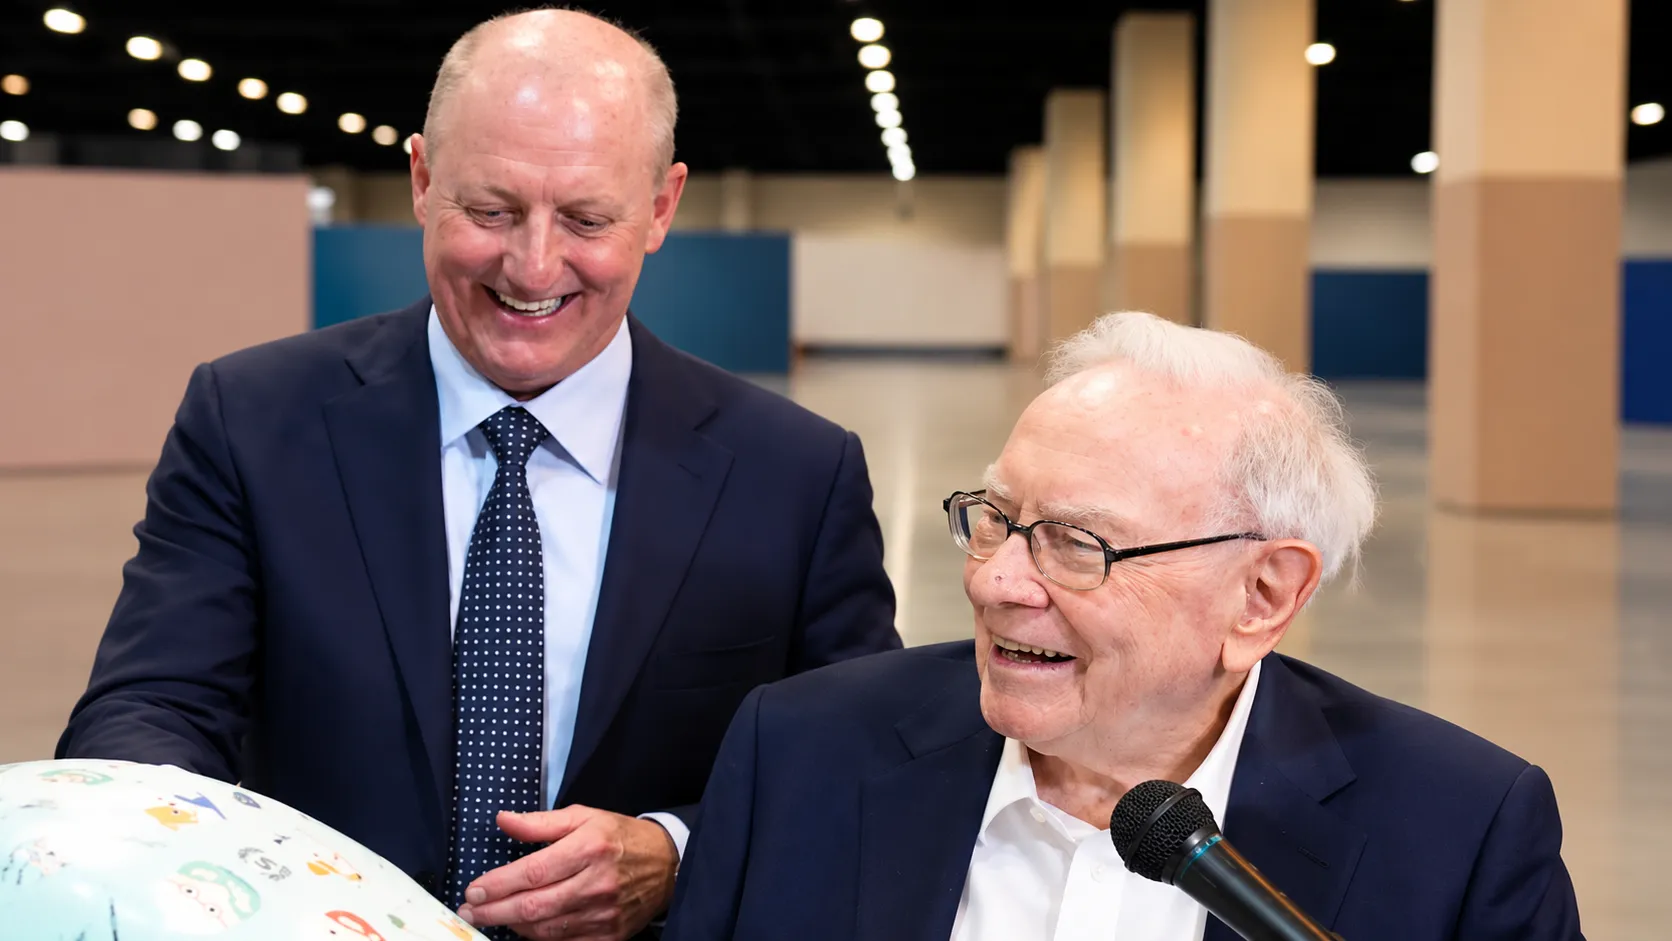
The increased spending marks an important development under Abel, who succeeded Warren Buffett as chief executive at the beginning of 2026. Buffett became increasingly selective about major acquisitions and share repurchases in his final years leading the company. Abel’s approach suggests a greater willingness to deploy available capital when management considers Berkshire shares attractively valued.
Share repurchases reduce the number of outstanding shares, potentially increasing existing investors’ proportional ownership. However, their financial benefit depends on the price paid and whether that spending delivers better long-term returns than acquisitions or other investments.
According to Berkshire’s November 7 earnings release, approximately 1.419 million Class A equivalent shares remained outstanding at September 30. The company continued to maintain substantial financial resources despite its increased repurchase activity.
Insurance Weakness Drives Operating Earnings Lower
The decline in Berkshire’s operating Profit was concentrated in its insurance operations. Underwriting earnings fell to $1.35 billion from $2.37 billion a year earlier, down about 43%. Insurance investment income also declined, falling to $2.73 billion from $3.18 billion.
GEICO, Berkshire’s major automobile insurer, faced pressure from higher claims costs and weaker underwriting performance. Insurance profitability depends on the relationship between premiums collected, claims paid and operating expenses. Rising claims expenses can significantly reduce earnings when premium increases fail to keep pace.
The insurance downturn contrasted with stronger results from several of Berkshire’s other major businesses. BNSF reported quarterly earnings of $1.73 billion, up from $1.45 billion a year earlier. Berkshire Hathaway Energy generated $1.61 billion, up from $1.49 billion.
Manufacturing, service and retail operations also improved, contributing $4.04 billion against $3.62 billion in the previous year’s quarter. These gains helped offset insurance losses but were insufficient to prevent the overall decline in operating earnings.
Net Profit Falls 28% as Investment Gains Shrink.
Berkshire’s reported net income declined approximately 28% to $22.11 billion from $30.80 billion in the third quarter of 2025. The larger decrease reflected changes in investment gains, which fell to $9.41 billion from $17.31 billion.
Unlike operating earnings, reported net income includes changes in the market value of Berkshire’s stock investments, even when the company has not sold those holdings. These accounting adjustments can create significant fluctuations between reporting periods without corresponding changes in the performance of its underlying businesses.
Berkshire has repeatedly cautioned investors against relying on quarterly investment gains and losses to evaluate its performance. Its operating earnings exclude those investment fluctuations and provide a separate view of results from insurance, railroads, energy and other businesses.
Large Cash Reserves Keep Investment Options Open
Berkshire ended September with approximately $356.9 billion in cash and equivalents, according to its quarterly financial disclosures. These substantial reserves give management flexibility to pursue acquisitions, buy publicly traded securities, or continue repurchasing Berkshire shares.
The company faces a different capital allocation challenge from technology businesses committing large portions of their operating cash to infrastructure expansion. As TechAmerica’s analysis of Big Tech shareholder returns found, heavy artificial intelligence investment has reduced the funds several major technology companies have available for stock repurchases.
For Berkshire, the immediate question is whether additional repurchases represent the most attractive use of its capital. Its considerable financial resources offer strategic flexibility, but large cash holdings can also weigh on investment returns when attractive opportunities remain limited.
What Investors Will Watch Next
Berkshire’s latest results reveal two separate trends: a more active share repurchase strategy and continued weakness in insurance profitability. Improved earnings from rail transportation, utilities, and manufacturing show the benefits of theconglomerate’ss diversified operations, but insurance remains a major source of earnings volatility.
Investors will be watching whether Abel maintains the faster pace of buybacks and how effectively Berkshire manages its remaining cash. A recovery in insurance underwriting would also strengthen operating results, while sustained claims pressure could continue limiting earnings growth.
The third-quarter figures show that Berkshire has considerable capacity to return capital to shareholders despite weaker operating Profit. Whether those repurchases create lasting value will depend on future business performance, Berkshire’s share valuation and management’s ability to identify attractive investments.