The US stock market correction that began in June may be approaching its final stage, according to Morgan Stanley strategists. The investment bank believes several developments could reduce uncertainty and create opportunities in economically sensitive stocks. However, investors may still face another period of sharp volatility before a sustained recovery begins.
In a November 2 report covered by Reuters, strategists led by Michael Wilson, Morgan Stanley’s chief U.S. equity strategist, said the market downturn was nearing completion. They identified the November 3 midterm elections, corporate earnings and improving financial conditions as important factors to monitor.
Why Morgan Stanley Believes the Market Correction Is Nearing Its End
One important signal comes from the difference between major stock indexes and the broader market. Although large technology companies have helped support benchmark indexes, many individual stocks have already fallen substantially. Morgan Stanley estimates that approximately 60% of Russell 3000 companies have fallen at least 20% from their respective levels since June.
Wilson believes the S&P 500 is now catching up with weakness that has already affected a large portion of the market. This pattern can emerge toward the end of a correction, particularly when previously resilient companies begin to decline. It does not establish that the market has reached its lowest point.
In an October 26 market outlook, Wilson described the downturn as part of a transition within the economic cycle. He cautioned that investor sentiment had not yet reached the extreme pessimism often associated with durable market bottoms.
AI Spending and Corporate Earnings Remain Major Risks
Artificial intelligence investment has become an important source of uncertainty for US equities. Technology companies continue committing substantial capital to computing infrastructure, but investors are increasingly examining whether those investments can generate sufficient financial returns.
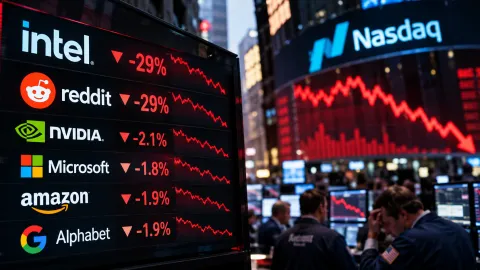
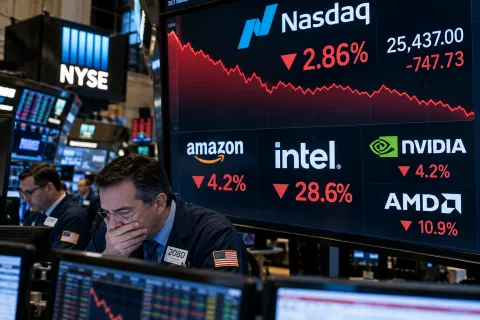
Concerns about financing costs, capital availability, and the sustainability of AI spending have also pressured technology valuations. The Nasdaq-100 lost trillions of dollars in market value during October, according to Reuters, bringing the technology-heavy index close to correction territory.
Morgan Stanley sees corporate earnings as another indicator of changing market conditions. Investors are paying greater attention to free cash flow, which reflects the cash a business generates after capital expenditures. Companies with strong reported profits but weaker cash generation may face closer scrutiny.
This shift could influence how investors evaluate technology businesses. Revenue growth alone may no longer justify elevated valuations when financing becomes more expensive. Companies that can demonstrate consistent earnings and reliable cash generation may be better positioned during the transition.
US Midterm Elections Could Remove Market Uncertainty
The November 3 midterm elections could mark another turning point. Morgan Stanley believes the results could reduce uncertainty about the political environment, even if immediate market volatility continues.
The bank noted that large-cap US stocks have historically gained approximately 15% during the six months following midterm election results. However, historical averages do not guarantee comparable returns in the current economic environment.
Wilson’s team also suggested that expectations of a Democratic sweep were already priced in. A bigger concern could emerge after the election, particularly if geopolitical tensions escalate or additional trade tariffs are introduced.
Renewed military confrontation involving Iran could affect energy prices and investor confidence. Further tariffs could raise business costs and complicate inflation expectations. Either development could interrupt a market recovery even after election-related uncertainty subsides.
Federal Reserve Policy and Liquidity Conditions
Financial conditions remain central to Morgan Stanley’s outlook. Higher borrowing costs, increased demand for capital, and elevated energy prices have pressured businesses and financial markets. Wilson believes these forces have contributed to the correction without requiring substantial additional monetary tightening.
The bank does not expect the Federal Reserve to respond immediately with interest rate cuts or other support measures. Instead, some liquidity relief could come from the US Treasury reducing its cash balance.
According to the Reuters report, Morgan Stanley anticipates theTreasury’ss cash holdings could decline from approximately $1.05 trillion to $850 billion by year-end. Such a reduction could help increase liquidity in the financial system, although its market impact would depend on the broader funding environment.
What the Outlook Means for Investors Heading Into 2027
Morgan Stanley’s assessment does not suggest that every stock has become attractively valued. Instead, its strategists see opportunities in financially stronger cyclical businesses whose valuations have already declined. These companies operate in industries that are particularly sensitive to changes in economic activity.
Wilson has highlighted quality businesses in areas such as capital goods, while emphasizing the importance of earnings durability. As investors reassess risk, a company’s ability to convert profits into cash could matter more than aggressive growth forecasts.
The distinction between an approaching market bottom and a confirmed recovery remains important. Even if the broader correction is nearing completion, major indexes could decline further before investor confidence improves.
For now, the outlook depends on how markets absorb earnings results, election developments and financing pressures. Morgan Stanley sees the possibility of a stronger environment heading into 2027, but its analysis leaves room for additional short-term losses. The next phase will test whether improving conditions can support a recovery beyond a narrow group of large technology companies.