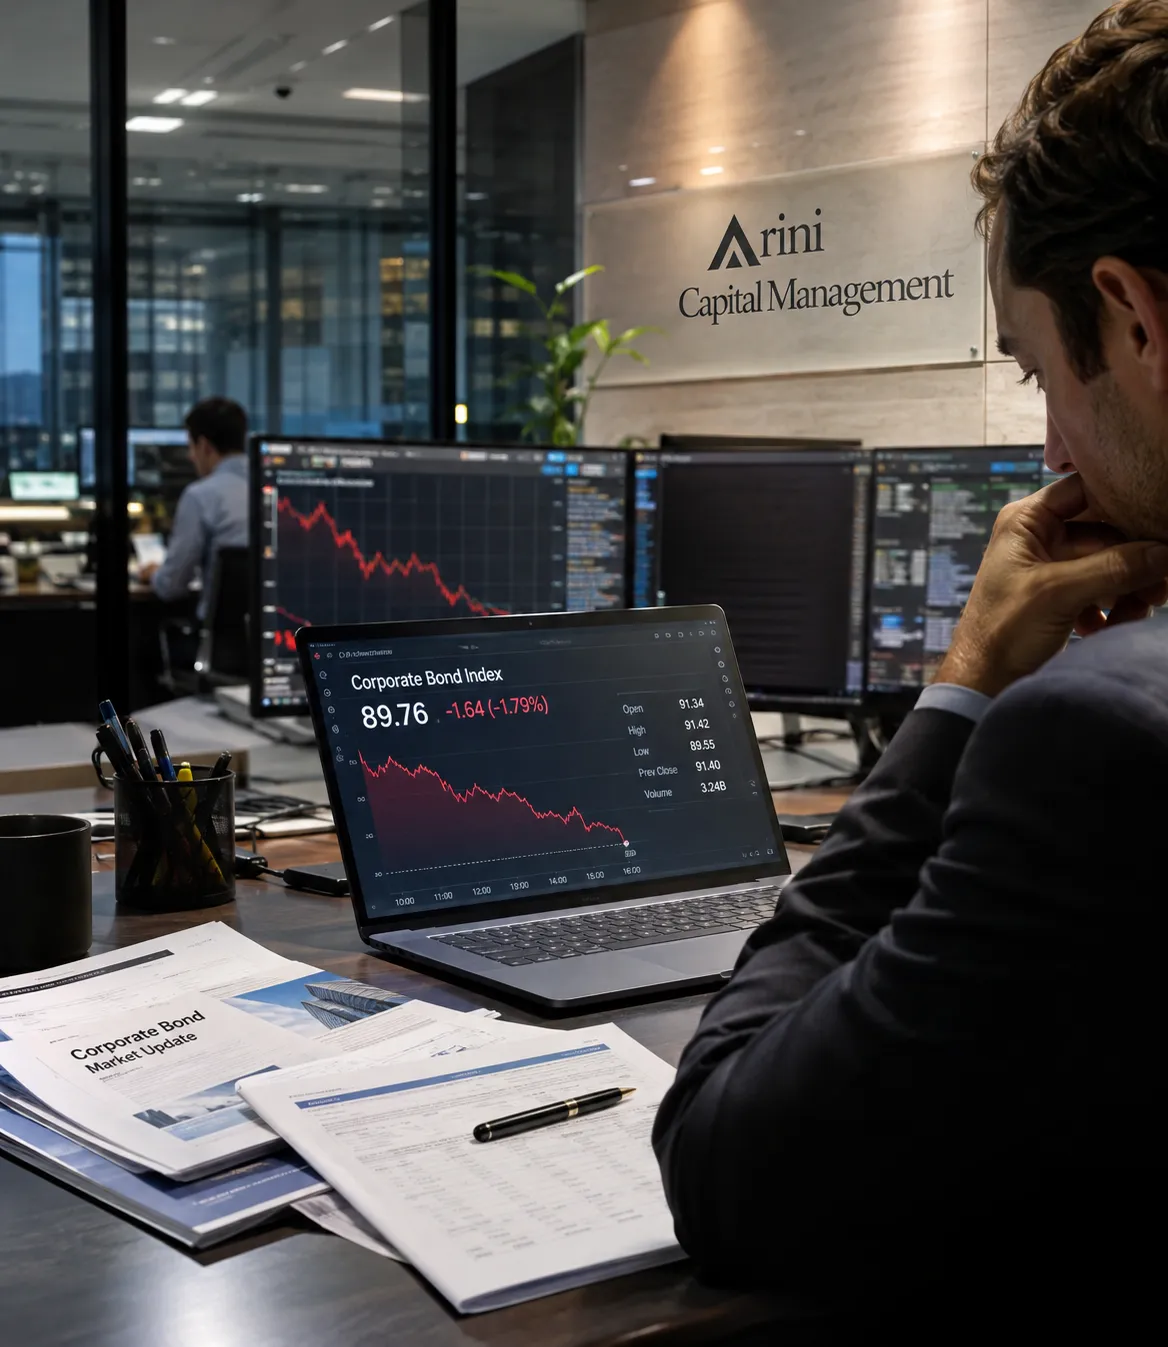
Arini Capital Management has sold approximately $800 million in debt holdings in recent weeks as mounting investment losses triggered margin calls from banks. The London-based investment firm, founded by former Credit Suisse trader Hamza Lemssouguer, is facing one of its most difficult periods since launching in 2021.
The firm’s flagship hedge fund, which manages roughly $7 billion, had lost more than 20% this year by mid-October, according to an October 30 report by The Wall Street Journal, citing people familiar with the matter. Subsequent reporting by Bloomberg indicated that losses had reached approximately 26% through October 23.
Arini Capital Management Faces Pressure From Debt Investments
Much of the pressure comes from investments in financially troubled telecommunications businesses. Arini has held debt linked to Altice International, Optimum Communications, Virgin Media and Brightspeed. Several of these companies face significant financial challenges, placing additional pressure on the value of their outstanding obligations.
Optimum has been approaching a potential Chapter 11 bankruptcy filing, while Brightspeed has considered similar proceedings, according to the Journal’s reporting. The fund has also faced losses connected to investments in Aston Martin, packaging company Multi-Color and building products manufacturer Cornerstone Building Brands.
The difficulties extend beyond individual corporate investments. Declining prices across European speculative-grade debt have weakened the market for securities that Arini specializes in trading. A broader selloff can make it harder for leveraged investors to maintain positions, even when they expect those investments to recover over time.
Margin Calls Force Sales of More Liquid Assets
Arini has reportedly sold more liquid debt investments to meet collateral demands associated with credit-default-swap indexes and other leveraged trades. A margin call occurs when a lender or trading counterparty requires additional collateral after an investment loses value or its risk increases.
These demands can create a difficult cycle for hedge funds. Selling assets raises cash to satisfy immediate obligations, but it can also reduce the portfolio’s flexibility and potentially lock in losses. The effect becomes more pronounced when multiple investors attempt to sell similar securities during a market downturn.
According to an October 30 Bloomberg report, investment managers including Pimco and Oaktree Capital Management have submitted bids for some of Arini’s high-yield debt holdings. Dealers have also discussed potential additional sales with prospective buyers.
European Credit Market Weakness Deepens Losses
Arini’s difficulties highlight growing stress in the riskier segments of European corporate credit. Higher borrowing costs, heavily indebted companies and concerns about future refinancing have weighed on bonds issued by weaker businesses.
Telecommunications companies have been particularly exposed because of their substantial debt burdens and changing competitive conditions. Falling bond prices can create problems for funds that rely on borrowing or derivatives to increase their investment exposure.
Bloomberg reported on October 28 that Arini’s flagship fund had declined approximately 12% during October through the 23rd. That brought its year-to-date losses to roughly 26%, illustrating how quickly pressure intensified in a portfolio previously known for aggressive credit investments.
Arini’s Wider Investment Business Remains Active
Despite the setback, Arini operates a substantially larger investment platform than its flagship hedge fund alone. Since its establishment in 2021, the firm has expanded from a specialist hedge fund managing approximately $1.3 billion into an alternative investment manager overseeing roughly $22 billion.
About one-third of its assets are invested in collateralized loan obligation funds, which have reportedly continued performing well. Arini has also recently closed a European direct-lending fund with about $4 billion in commitments, suggesting its broader credit operations remain active despite the flagship fund’s difficulties.
The firm has also seen leadership changes. Gavin Yates, who headed its U.S. business, departed in August and is expected to establish a distressed-debt investment team at Citadel next year, according to the Journal.
The immediate question is whether Arini can stabilize its flagship portfolio without further substantial asset disposals. Its experience also illustrates a broader risk in leveraged credit investing: losses in concentrated positions can trigger collateral demands that force sales elsewhere in a portfolio. The outcome will depend partly on market conditions and the performance of its remaining investments.