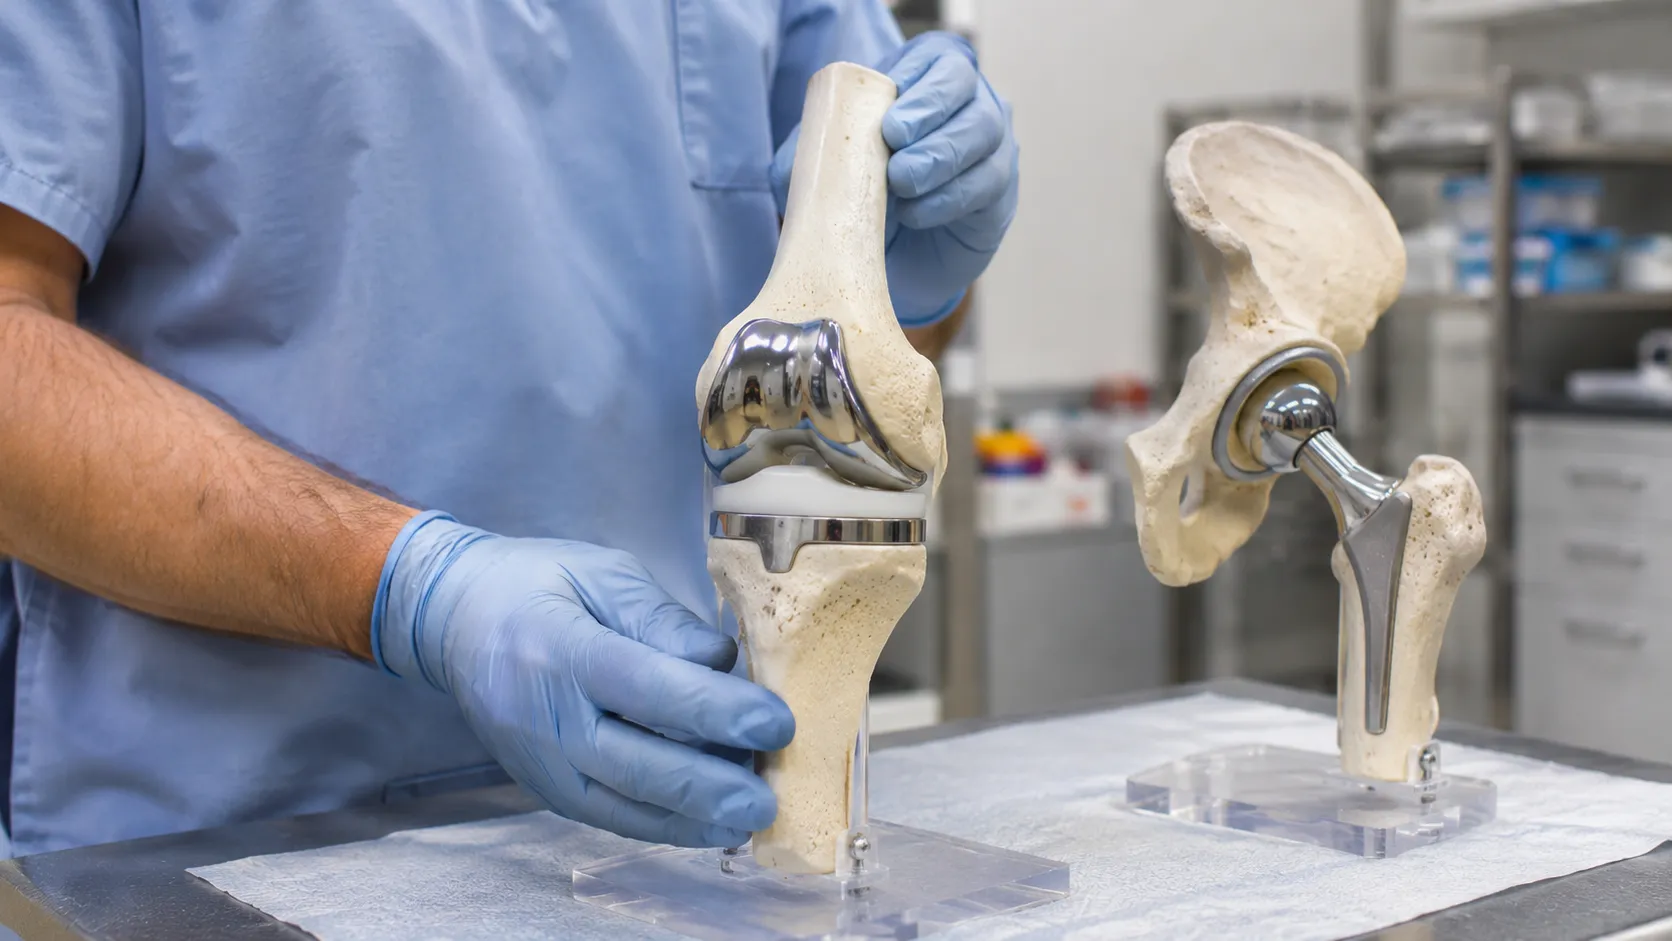
Zimmer Biomet raised the lower end of its 2026 sales growth forecast after stronger hip sales helped offset declining knee revenue. The Nov. 4 earnings report highlighted uneven performance across its joint replacement business as the company reorganises its U.S. sales force.
The orthopaedic device maker now expects reported annual revenue growth of 4.4% to 4.9%, compared with 3.9% to 4.9% previously. The upper end remains unchanged.
Zimmer Biomet raises guidance despite mixed results
Third-quarter revenue reached $2.06 billion, up 3.1% from a year earlier. Net income fell 17% to $191.6 million, while adjusted diluted earnings per share remained at $1.90.
The company’s earnings release showed contrasting results in its two main joint replacement categories. Reported growth includes currency effects; constant-currency growth removes those effects.
| Business | Third-quarter sales | Year-over-year reported change | Constant-currency change |
|---|---|---|---|
| Knee implants | $767.5 million | −3.1% | −2.6% |
| Hip implants | $536.5 million | +6.0% | +7.0% |
Zimmer Biomet also raised its adjusted annual earnings forecast to $8.50 to $8.60 per share, from $8.47 to $8.59. It also raised its organic constant-currency sales growth forecast to 3% to 3.5%.
The organic measure excludes the contribution from the Paragon 28 acquisition through its first anniversary. It therefore provides a different view of growth from the reported revenue forecast, which includes acquisition and currency effects.
Cash generation also strengthened the quarterly results. The company reported $560 million in operating cash flow and $372.4 million in free cash flow.
The figures show why management can raise its forecast while acknowledging problems in knees. Sales growth elsewhere is supporting the total, but the results do not yet demonstrate a recovery in the company’s largest implant category.
Executives and analysts differ on knee demand.
CEO Ivan Tornos attributed the knee shortfall primarily to commercial execution during the shift to a fully dedicated sales force. Competition also weighed on the business, but he declined to characterise the results as evidence of a broader market slowdown.
On the earnings call, Tornos pointed to stronger hip sales and growth in ambulatory surgery centres. He also said cancellation rates were steady and pricing performance had improved from the previous quarter.
That assessment differed from Stryker’s explanation for its own weaker hip and knee results. The competitor cited affordability and insurance challenges, while J.P. Morgan analyst Robbie Marcus argued that weakness across major knee suppliers suggested market pressures.
Knee implants remain a substantial part of Zimmer’s business, accounting for roughly 37% of quarterly revenue. Their performance therefore remains important even as growth in other product categories supports the company’s overall outlook.
The sales transition also makes the quarter harder to interpret as a measure of underlying procedure demand. Changes in how a manufacturer serves surgeons can affect its own sales without establishing that fewer patients are receiving joint replacements.
For readers assessing the outlook, the distinction is between company performance and market conditions. Tornos emphasised execution problems within Zimmer, while the analyst’s interpretation placed more weight on results across competing suppliers.
Monogram robot awaits its next regulatory step.
Zimmer Biomet is preparing an FDA submission for an autonomous version of the Monogram surgical robot acquired last year. Management is targeting a launch in the first half of 2027, subject to regulatory clearance.
The existing Monogram system is cleared for total knee replacement procedures. That clearance does not authorise the proposed autonomous version, and the launch timetable remains a company projection.
Management expects the Monogram platform to attract surgeons who do not currently use robotic technology. That is a commercial expectation, and the earnings update does not establish how quickly hospitals or surgeons would adopt the proposed system.
The distinction between assistance and autonomy also runs through other AI-enabled medical equipment. Software that supports a surgeon’s decisions or movements does not necessarily perform a procedure independently.
TechAmerica’s coverage of surgical robot guidance examines the evidence and labelling questions surrounding these systems. That broader regulatory work does not establish clearance for Zimmer’s proposed product.
Tornos said clinical testing produced no patient safety reports and showed improved accuracy, MedTech Dive reported. Those statements reflect management’s account of the research, not independent confirmation of better patient outcomes.